
The DRC’s mineral power has long rested on the scale of its deposits. In 2026, Kinshasa is trying to extend that power into the data, processing, infrastructure and markets surrounding them.
The starting point is the resource base itself. The Democratic Republic of the Congo (DRC) accounted for 74% of global cobalt mine production in 2025, according to UN Trade and Development (UNCTAD), while also ranking among the world’s largest copper producers. Yet geological knowledge of the country remains incomplete: Reuters reported in September that only about 20% of the DRC had been systematically explored. A $180 million national mapping program, launched under a three-year contract with Spain’s Xcalibur, is intended to improve that picture and feed a national geological databank.
That effort matters because geological information determines where exploration takes place and how projects are assessed. Kinshasa is seeking greater state control over that information, including by distinguishing between freely available basic data and more sensitive datasets whose access could generate revenue or be assessed against strategic interests. The government has also signaled that sovereignty over mineral resources and related data is a central part of its policy.
Control over exports is the next part of the strategy. In June, the DRC banned exports of copper and cobalt concentrates, with limited possibilities for exemptions, as part of an effort to push more processing into the country. The policy follows the introduction of cobalt export quotas and a strategic quota system designed to give the state greater influence over supply.
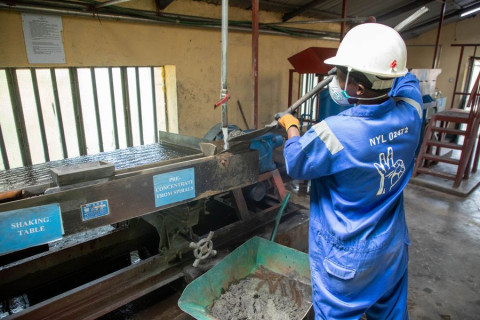
The shift, however, is not simply from raw minerals to refined products because the DRC already exports a large share of its copper in processed form. The country shipped 1.72 million tonnes of copper in the first half of 2026, with refined cathodes accounting for about 86% of total exports. The more important question is whether further processing, industrial activity and mineral-related supply chains can capture a larger share of value inside the country. UNCTAD’s current work on the DRC specifically focuses on identifying realistic pathways for value addition and economic diversification beyond the export of primary commodities.
Kinshasa is simultaneously working to influence where its minerals go. Copper exports to the United States reached a record 53,290 metric tons in July 2026, giving Congolese copper 23.9% of total US copper imports that month. Reuters also reported that the share of DRC copper shipped to the United States and Europe doubled in the first half of 2026 compared with 2025. China, however, remains central: it accounted for 39.4% of the DRC’s copper exports in July.
That combination points to diversification rather than a break with China. Chinese-linked companies, including CMOC, Huayou Cobalt and Zijin, remain major players in the Congolese mining sector. The challenge for Kinshasa is therefore not simply to find new buyers, but to gain greater influence over the terms, destinations and commercial channels through which minerals produced in the DRC are sold.
State-owned Gécamines is becoming an important instrument in that effort. In December 2025, the US International Development Finance Corporation announced a proposed equity investment in a Gécamines-Mercuria joint venture focused on the commercialization of copper, cobalt and other critical minerals. Gécamines has also expanded its role in marketing production from mines in which it holds minority interests, giving the state miner a larger commercial role even where Chinese or other foreign companies operate the assets.
The US–DRC Strategic Partnership Agreement adds a formal international framework to these efforts. Signed in December 2025, the agreement created a Strategic Asset Reserve and gives US persons a right of first offer on designated projects. It also links critical minerals to infrastructure, industrialization and local value addition. In February 2026, the partnership formally entered its implementation phase when the two governments launched the Joint Steering Committee and the DRC designated its initial Strategic Asset Reserve assets. In September, Kinshasa went further by creating a DRC-USA Task Force to accelerate implementation.
Infrastructure is essential to making that strategy work. The Lobito Corridor is being developed as an alternative route linking the DRC’s Copperbelt to the Atlantic through Angola. DFC and DBSA reached financial close on $786 million for the Lobito railway project, while MIGA has separately provided $62.6 million in guarantees for Mota-Engil’s investment in the Angolan railway concession. A new USTDA-backed feasibility study is also examining hydropower expansion and electricity distribution in Lualaba and neighboring Zambia, targeting more reliable power for mining operations and more than 3 million people.
The limits of the strategy are equally important. Better geological data does not automatically produce new mines. Export restrictions require sufficient domestic processing capacity. New buyers do not eliminate China’s position in production and trade. And new transport corridors cannot solve shortages in electricity, financing, technology or skilled labor on their own. UNCTAD notes that building diversified domestic value chains requires long-term investment, stronger capabilities and coordinated policy support.
Taken together, the changes underway point to a broader shift in how Kinshasa approaches its mineral wealth. The DRC is not abandoning extraction; it is trying to gain more influence over the layers that surround it — geological intelligence, regulation, processing, state marketing, energy, transport and final markets.
That distinction is important. Mineral wealth gives the DRC an unusually strong starting position, but strategic leverage depends on how much of the value chain the country can actually influence. The measures introduced in 2026 show Kinshasa moving in that direction, while also revealing how much remains dependent on foreign capital, technology, infrastructure and commercial partners.